Mortgage Rates Near 6%: What It Means for You
Mortgage rates have been rising again this autumn. On 5 October, the average five-year fixed rate hit 6% for the first time in about three years, according to Moneyfacts. If you are buying in Bramhall or Cheadle Hulme, or your fixed deal ends soon, here is what has changed, why it has happened and what you can do about it.
What has happened to mortgage rates?
Moneyfactscompare.co.uk reported on 5 October that:
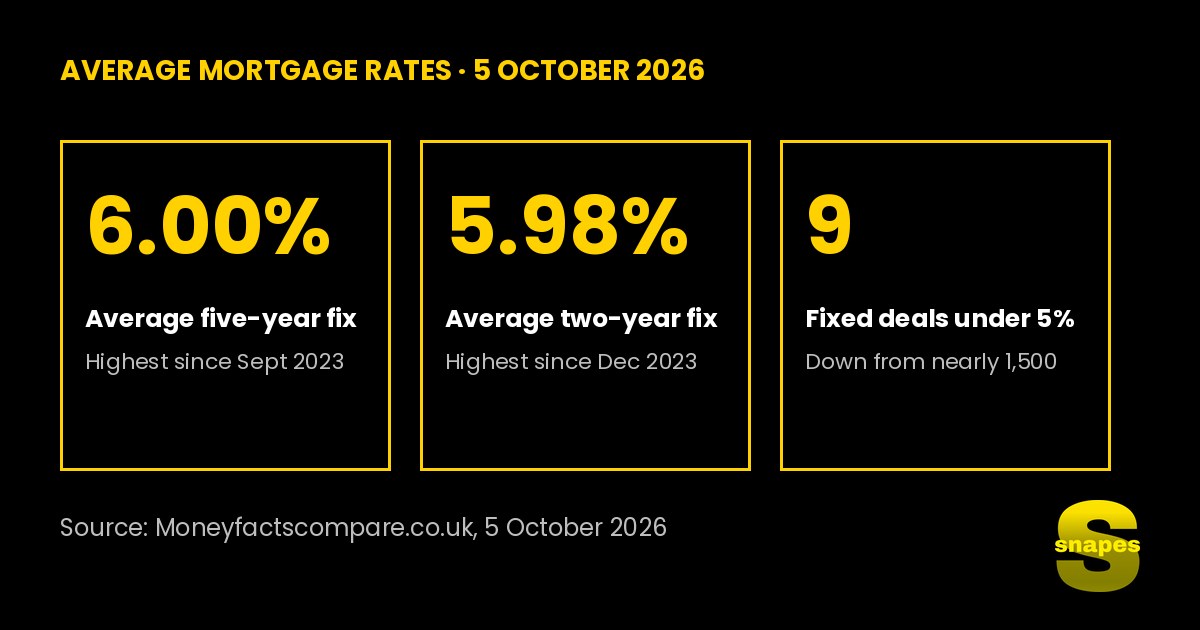
the average five-year fix reached 6.00%, the highest since September 2023
the average two-year fix reached 5.98%, its highest since mid-December 2023
fixed deals priced below 5% fell from nearly 1,500 at the start of September to just nine
Rachel Springall, Finance Expert at Moneyfactscompare.co.uk, said this "shows just how quickly the mortgage market has shifted for borrowers searching for the lowest rates."
Why are rates going up?
The Bank of England has kept Bank Rate at 3.75%. So why are mortgages more expensive?
Lenders price fixed-rate mortgages using swap rates, which track what the markets expect interest rates to do over the next few years. Those expectations have risen. Rachel Springall told ITV News that as wholesale funding costs climb on the back of rising gilt yields, "fixed rate adjustments are somewhat inevitable."
Inflation is part of the picture too. The Office for National Statistics reported that inflation rose to 3.1% in August, up from 2.9% in July. At its meeting on 17 September, the Bank of England's Monetary Policy Committee voted 6–3 to hold rates, with three members wanting a rise to 4%, as HomeOwners Alliance reports.
The next decision is due on Thursday 5 November, a week after the Budget on 28 October. Several economists, including Capital Economics and Barclays, expect a rise. Others, such as AJ Bell, think rates could stay where they are. Nobody knows for certain.
Some early signs of relief
It is not all bad news. A few big lenders have started to trim their rates again:
NatWest cut selected fixed rates from 15 October, with a two-year fix at 5.04% and a five-year fix at 4.98% (What Mortgage, 14 October).
HSBC cut rates on the same day. Santander, Halifax and Yorkshire Building Society made cuts the week before.
By 14 October the averages had eased slightly, to 5.96% for a two-year fix and 5.99% for a five-year fix. Nicholas Mendes of John Charcol said NatWest's move signals "a clear wish to compete for business." Lenders still want to lend; the challenge for most borrowers is affordability.
What it means for buyers in SK7 and SK8
Rates vary a lot depending on your deposit. Rightmove's figures, quoted by Tembo on 15 October, show:
5% (95% LTV): two-year fix 6.03%, five-year fix 6.02%
10% (90% LTV): two-year fix 5.66%, five-year fix 5.61%
25% (75% LTV): two-year fix 5.41%, five-year fix 5.39%
40% (60% LTV): two-year fix 5.10%, five-year fix 5.08%
A bigger deposit still makes a real difference. The best deals are also well below the average. The gap between an average deal and one of the best on the market can be worth well over £100 a month.
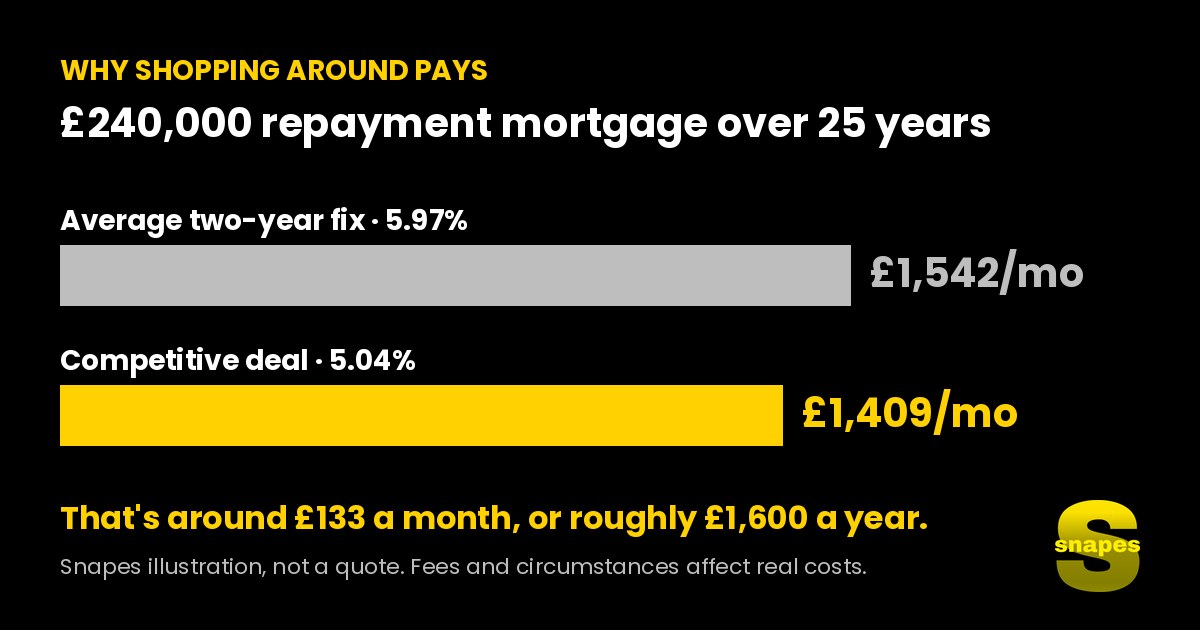
An example: on a £240,000 repayment mortgage over 25 years, a rate of 5.97% costs about £1,542 a month. At 5.04% it is about £1,409. That is a saving of around £133 a month, or roughly £1,600 a year. (Our own illustration, not a quote. Fees and your circumstances will affect the real figures.)
Looking to borrow a different amount?
Why not try our mortgage calculator and then book to see what exclusive deals we can get you.
For context, the Office for National Statistics puts the average Stockport house price at £318,000 in July 2026, up 4.2% on a year earlier. A buyer with a 25% deposit on a home at that price would borrow about £238,500. Prices in Bramhall and Cheadle Hulme are typically higher than the Stockport average, so getting the right deal matters even more here.
What it means if your fixed deal is ending
If your fixed rate ends in the next six months, now is the time to act. Sarah Tucker of HomeOwners Alliance advises: "If your current mortgage deal ends within the next six months, start looking at your options now."
Many lenders let you secure a new rate months in advance. If rates then fall before your deal starts, a good adviser can often switch you to a cheaper option.
Five steps to take now
Check when your current deal ends and diarise a date six months before.
Get advice before you make an offer on a home, so you know exactly what you can borrow and what it will cost.
Compare the whole market, including product fees, not just the headline rate.
Think about your deposit. Moving into a lower loan-to-value band can cut your rate.
Do not try to time the market. With a Bank of England decision on 5 November, securing a rate now can protect you if prices rise.
Landlords and tenants
Higher mortgage costs also affect buy-to-let landlords, especially those remortgaging. Demand for rented homes locally remains strong: the ONS puts average private rents in Stockport at £1,119 a month in August 2026, up 5.4% on a year earlier. If you are a landlord weighing up your options, our lettings team in Bramhall and Cheadle Hulme can help.
Talk to our Bramhall or Cheadle Hulme team
Buying, moving or remortgaging? Get mortgage advice to find out what you can borrow and what it will cost before the next rate decision.
Thinking of selling or letting? Book a free, no-obligation valuation or lettings appraisal with our Bramhall or Cheadle Hulme office.
For any other enquiries, email [email protected] or pop into our Bramhall or Cheadle Hulme office.
This article is general information, not financial advice. Your home may be repossessed if you do not keep up repayments on your mortgage.
Sources: Moneyfactscompare.co.uk (5 October 2026); ITV News (5 October 2026); What Mortgage (14 October 2026); Tembo, using Rightmove data (15 October 2026); Bank of England (17 September 2026); HomeOwners Alliance (updated October 2026); Office for National Statistics, Stockport house prices and rents (published October 2026).